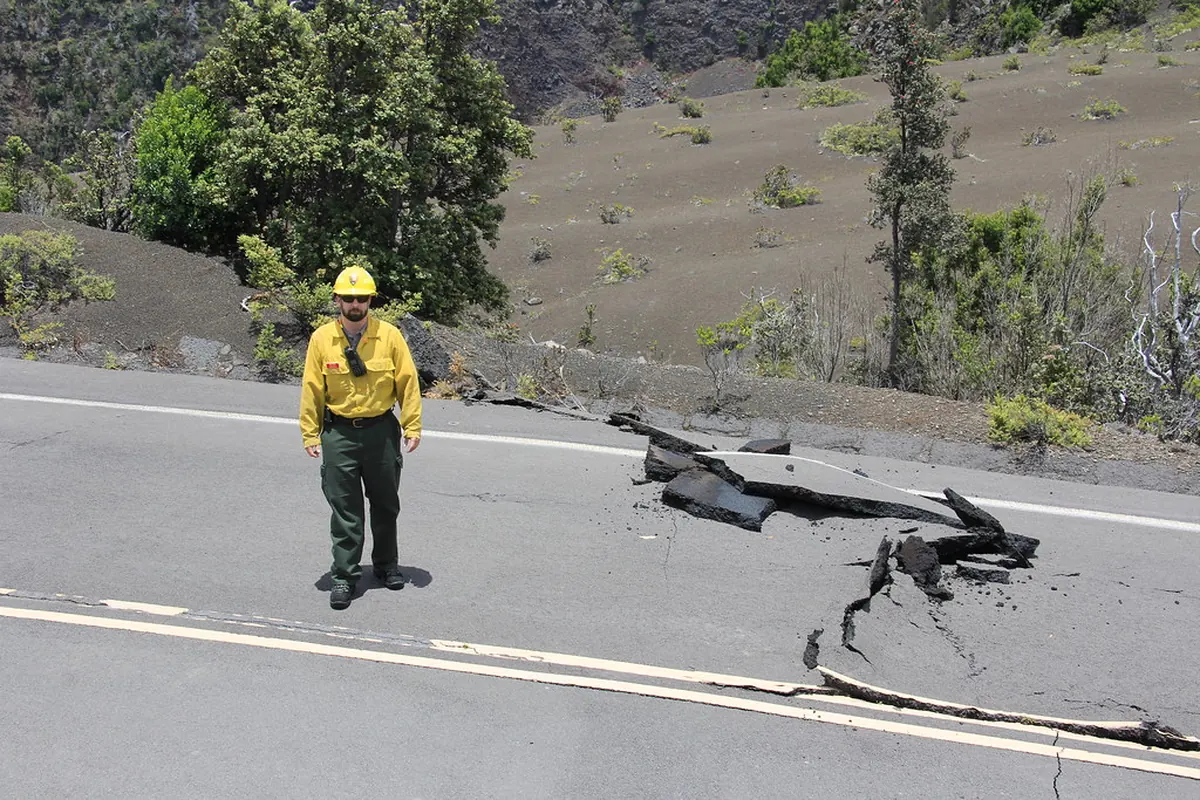
Earthquake coverage is separate
Standard homeowner and commercial property forms usually exclude earth movement, including earthquake. Coverage typically comes from an endorsement or separate policy, and it usually carries a percentage deductible tied to the coverage limit, often far higher than the regular deductible. Our deductible impact calculator shows what that means in dollars.
What quake damage looks like
- Cracked drywall and plaster, often throughout the house
- Foundation cracking, settlement and slab damage
- Chimney and masonry damage
- Broken water lines, water heaters and fixtures
- Doors and windows that no longer close properly
- Damage to contents and built-ins
Why earthquake claims get disputed
Cosmetic cracking and structural damage can look similar. Carriers may attribute cracks to settlement, frost heave or age rather than the quake. And because the deductible is high, small differences in the estimate determine whether any payment is owed at all. Pre-quake photos, inspection reports and engineering evaluations become very important.
Aftershocks and multiple events
Large Alaska quakes are followed by thousands of aftershocks. Policies differ on how they treat damage from a sequence of events, which affects how many deductibles apply. Read your endorsement carefully.
Frequently asked questions
Does my homeowner policy cover earthquakes?
Usually not. Earthquake coverage is generally added by endorsement or a separate policy. Check your declarations page.
Why is my earthquake deductible so high?
Earthquake deductibles are typically a percentage of the dwelling limit, so a 10% deductible on a $400,000 limit is $40,000. Figures here are illustrative.
Can appraisal resolve whether cracks came from the quake?
Appraisal values the loss. Whether some damage was caused by the earthquake can overlap with coverage, and how far a panel can go varies, so get advice if causation is the main issue.