Where homeowner claims go short
Most homeowner disputes in Alaska are not denials. They are estimates that leave things out. A typical example: the carrier pays to replace water-damaged drywall in a basement but omits the insulation behind it, the vapor barrier, the baseboard heat that had to come off the wall, and the extra drying days a cold slab requires. Each item is small. Together they can be a large part of the real cost.
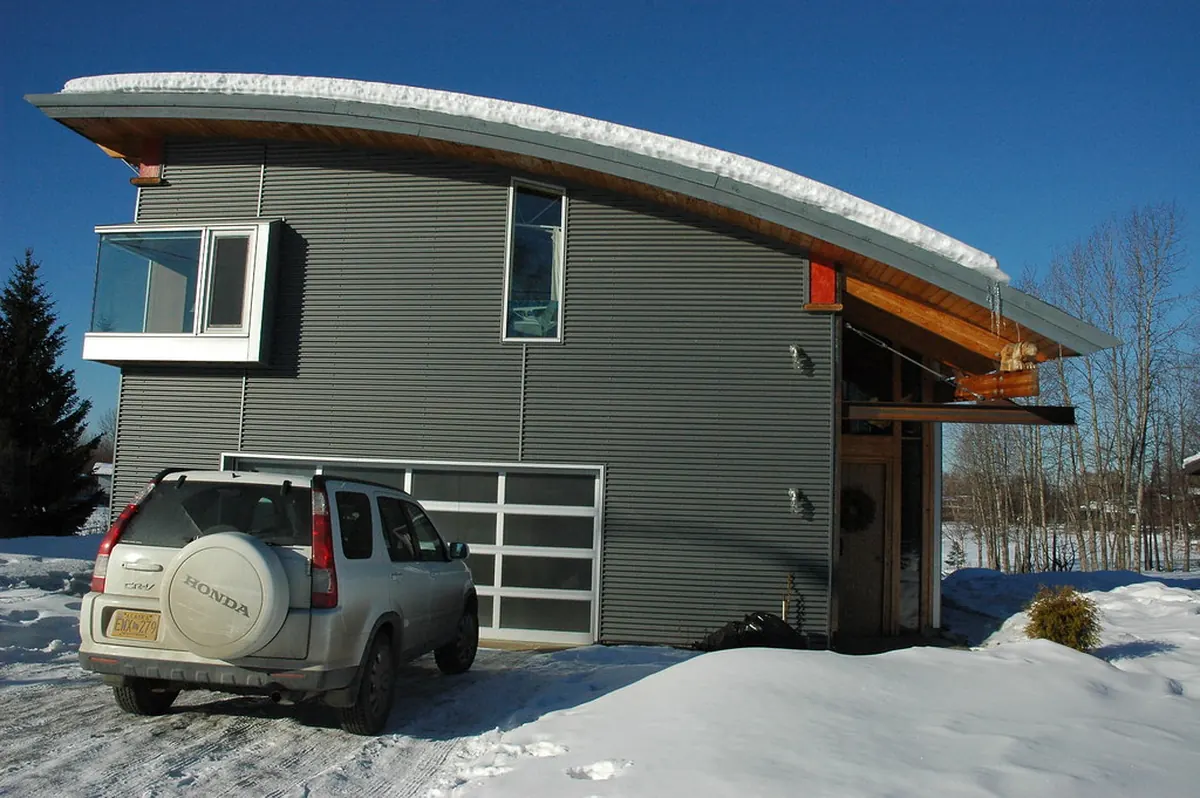
Housing we see across the state
- 1970s and 1980s split-levels and bi-levels in Anchorage, Eagle River and Fairbanks, often with additions, wood stoves and older electrical service.
- Newer stick-built homes and manufactured homes in the Mat-Su, where rapid growth means many owners are on their first claim.
- Log homes and cabins in the Interior, on the Kenai Peninsula and off the road system, where specialty labor is scarce.
- Older wood-frame homes on steep, wet lots in Juneau, Ketchikan and Sitka, some on pilings or with long stair access.
- Condos and townhomes where the association's master policy and your HO-6 have to be read together.
What a homeowner appraisal includes
We inspect the property, measure every affected area and prepare a line-item estimate that reflects current material and labor costs in your area, plus freight and travel where they apply. We compare it with the carrier's estimate item by item and show you exactly where the two differ and why. If appraisal is invoked, that estimate becomes the basis for our work on the panel.
Other structures and contents
Detached garages, shops, greenhouses, sheds and carports are common in Alaska and often carry heavy snow-load and wind exposure. Contents claims after fires or water losses can involve hundreds of items. Both can go through appraisal when the dispute is about value rather than coverage.
Frequently asked questions
Can contents be appraised, or only the building?
Contents can be appraised when the disagreement is about value. A clean inventory with ages, quantities and replacement prices makes that much easier.
I already accepted a payment. Is it too late?
Not necessarily. Many policies allow supplemental claims and appraisal after an initial payment, but deadlines apply. Check your policy and act promptly.
Do you handle manufactured homes?
Yes. Manufactured and modular homes have their own pricing and parts-availability issues, which we account for in the estimate.