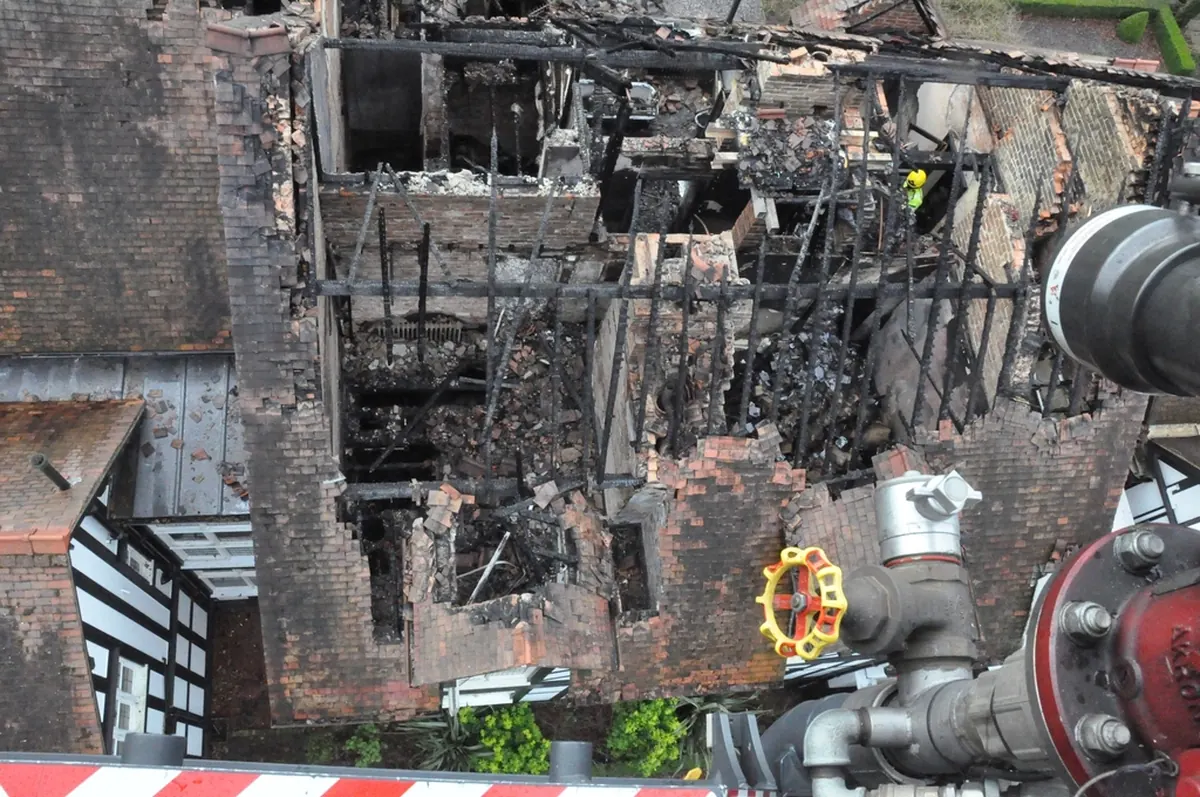
Fire risk in Alaska
Many Alaska homes rely on wood stoves, oil furnaces and space heaters through long winters, and chimney fires are a recurring cause of loss. In summer, wildfire season brings a different risk. The 1996 Miller's Reach Fire near Big Lake and Houston destroyed hundreds of structures, and more recent fires near Willow, Sterling and the Parks Highway corridor have damaged or destroyed dozens of homes. Even homes that do not burn can be affected by smoke and ash for weeks.
Where fire claims are disputed
- Smoke cleaning versus replacement. Whether drywall, insulation, carpet and HVAC can be cleaned or must be replaced.
- Odor. Residual smoke odor after cleaning is a common point of contention.
- Structural char. How much framing must be replaced versus sealed.
- Code upgrades triggered by significant rebuilding.
- Contents. Valuation of hundreds of household items, including depreciation.
- Debris removal and limits on that coverage.
Total losses
When a home is a total loss, disagreements often focus on the cost to rebuild rather than the policy limit. Remote locations, limited contractor availability and short building seasons all push costs up, and estimates built on generic pricing can fall well short.
Our approach
We inspect the property, review any cause-and-origin and industrial hygiene reports, and build a room-by-room estimate. For contents, we help organize the inventory so that each item has a description, age and replacement price that a panel can evaluate.
Frequently asked questions
Is wildfire smoke damage covered if the fire never reached my home?
Smoke damage is often covered as part of the fire peril, but carriers may dispute how much damage occurred. Prompt documentation and testing can help.
Do you handle contents inventories?
Yes. We help organize and value contents so they can be presented clearly in appraisal.
What if my policy limit is too low to rebuild?
Appraisal sets the amount of loss but cannot exceed policy limits. Extended or guaranteed replacement cost endorsements may matter.