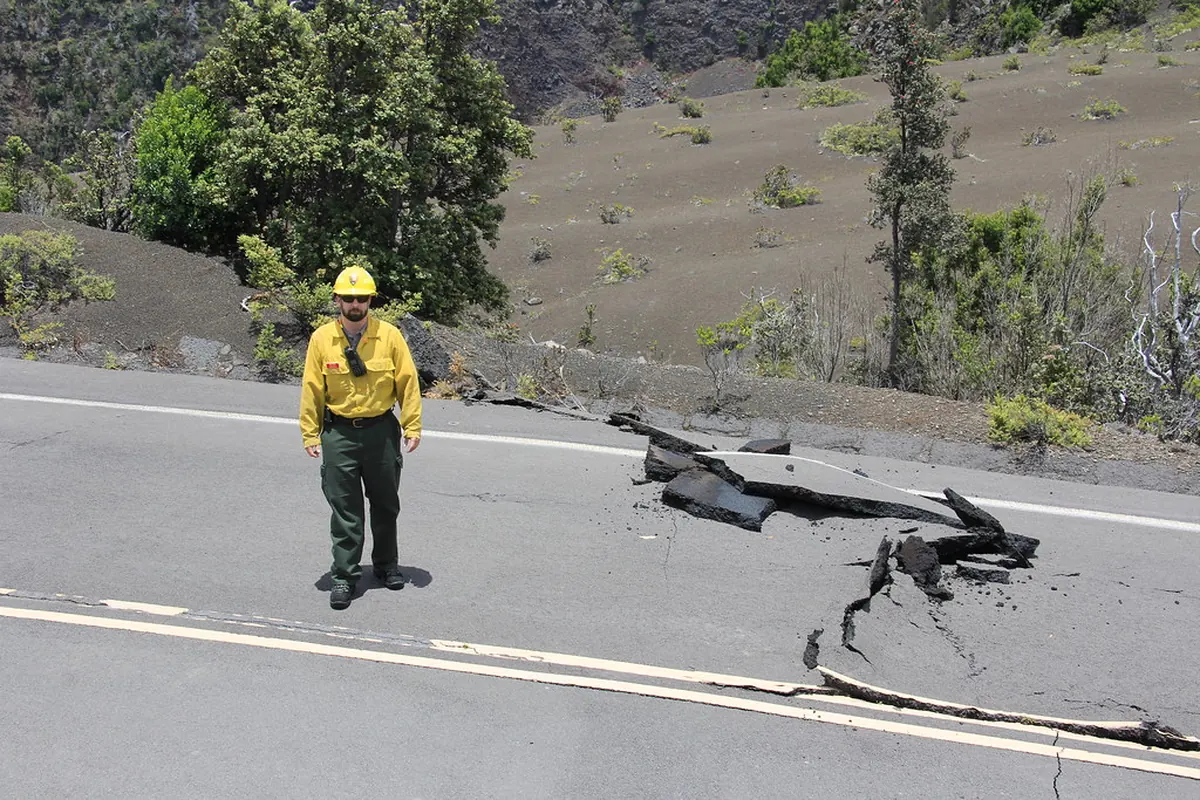
On November 30, 2018, a magnitude 7.1 earthquake struck just north of Anchorage. Damage spread across the Municipality of Anchorage and the Mat-Su. For owners who carried earthquake coverage, the claims that followed raised several recurring issues.
Earthquake coverage is separate
Standard homeowner policies typically exclude earth movement. Coverage usually comes from an endorsement or separate policy. If you are not sure whether you have it, check your declarations page for an earthquake endorsement and deductible.
Percentage deductibles
Earthquake deductibles are usually a percentage of the coverage limit. On a home insured for $400,000, a 15% deductible is $60,000. That means small differences in the estimate can decide whether anything is paid. These figures are illustrative.
Cracks: quake, settlement or age?
Many homes had cracks before the quake. Carriers often attribute cracks to settlement, frost heave or age. Pre-quake photos, real estate listing photos and inspection reports can help show what changed. Engineers may be needed for foundation questions.
Drywall scope
Earthquake drywall damage is often scattered across many rooms. Estimates that repair isolated cracks without accounting for continuous wall and ceiling planes, texture matching and paint can fall short.
When appraisal helps
If coverage is accepted and the dispute is about the extent and cost of repairs, appraisal may help. If the carrier says the damage was not caused by the quake, that may involve coverage questions that an attorney should review.
Preparing for the next one
- Photograph your home's interior and foundation now, and save the files off-site.
- Review your earthquake coverage and deductible.
- Know where your gas, water and electrical shutoffs are.